Understanding the 2026 NH State Ballot Questions
New Hampshire voters will see two statewide ballot questions on their Nov. 3 ballots. Question 1 asks whether to eliminate the county office of register of probate. Question 2 asks whether to limit growth in local school property taxes and spending in school administrative unit (SAU) central offices. This article explains what each choice means so you can make up your own mind. It does not recommend a yes or no vote.
The state constitution creates the elected county office of register of probate. Years ago, these officials handled records for probate courts, which deal with wills, estates, and guardianships. A court reorganization in 2011 transferred the main court duties to the state court system. The office now has limited duties.
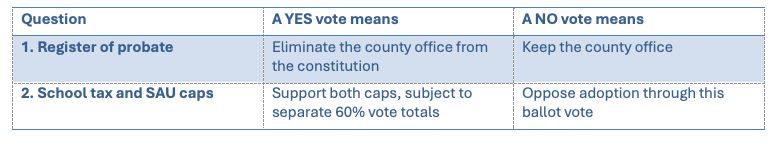
What does my vote mean?
· YES: Remove the office of register of probate from the state constitution.
· NO: Keep the office in the state constitution.
· BLANK: Do not cast a vote on this question. Election officials count only yes and no votes when they measure support or opposition.
A constitutional amendment needs at least two-thirds of the yes and no votes to pass. In 2022, a similar proposal received about 62.9% support but did not reach that threshold. In 2026, lawmakers approved legislation to place this measure on the ballot by votes of 325 to 15 in the House and 23 to 1 in the Senate.
The official 2026 ballot question starts by asking whether voters favor eliminating the office of register of probate. It then shows the proposed changes to two articles of the state constitution. Do not confuse this office with the register of deeds, which handles land records. Question 1 concerns the register of probate only.
The candidates for the (largely ceremonial) office still appear on the ballot in the current election since the position has not been eliminated.
This question asks voters to consider two different limits. One would control how fast the local school property tax levy can grow. The other would limit the central office budget of a school administrative unit, or SAU, to 6% of the combined budgets of its school districts, after officials exclude certain bond costs.
A tax levy means the total dollars a school district raises through local property taxes. It does not mean the tax rate on each home. An SAU central office handles shared services, such as the superintendent, payroll administration, and district finances.
What does my vote mean?
· YES: Support both limits. Each limit takes effect only if at least 60% of the yes and no votes across its own district or SAU support it.
· NO: Oppose both limits through this ballot question. A limit that fails does not take effect under this vote.
· BLANK: Cast no vote on this question. A blank answer does not count as a yes or a no.
You cannot choose yes for one limit and no for the other. However, election officials count results separately for each school district and for each SAU. So a district cap can pass even if the SAU cap fails, or the reverse.
What would the school tax limit do?
Officials would start with the previous year’s local school property tax levy, without qualifying bonded capital costs. They would then allow an increase for inflation and growth from newly taxable property, such as new construction or improvements. The law uses the March Northeast Consumer Price Index measure. It does not count higher prices for existing homes or a townwide reassessment as new property growth.
Example: If the prior levy, after exclusions, equals $10 million, inflation equals 3%, and net new taxable property growth equals 1%, the formula sets a $10.4 million limit before separately accounting for qualifying bonded capital costs. These figures illustrate the calculation; they do not describe any local district.
What would the 6% SAU limit do?
The limit would cover central office administration, including superintendent services, finance, payroll, human resources, purchasing, district information technology management, legal services, and certain district curriculum leaders. The law does not count classroom instruction, school support staff, special education services, transportation, food services, or building maintenance as central office administration.
Officials add the budgets of all districts in the SAU, leave out qualifying bonded capital costs, and take 6% of the remaining total. The SAU central office budget must stay within that figure unless voters or the proper local governing body approve an override.
How does this work when an SAU serves more than one town and/or school district?
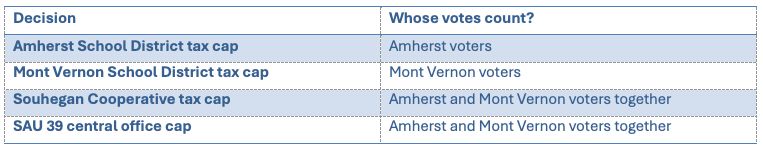
As an example, SAU 39 serves the Amherst, Mont Vernon, and Souhegan Cooperative school districts. Souhegan School District serves both Amherst and Mont Vernon. Therefore, the same voter may help decide more than one cap as illustrated in Table 1 below.
For the joint decisions, officials add the actual yes and no votes from both towns. They do not average the towns’ yes percentages
Example: Amherst casts 600 yes and 400 no votes. Mont Vernon casts 100 yes and 400 no votes. Amherst reaches 60% yes and passes its own district cap. Mont Vernon reaches 20%. Together the towns reach 700 yes votes out of 1,500, or 46.7%. In this example, the Mont Vernon, Souhegan, and SAU 39 caps fail.
When would the caps start?
A cap that passes in November 2026 starts with fiscal year 2028, which begins July 1, 2027 for school districts that use that fiscal calendar. It covers fiscal years 2028 and 2029. The law calls for another vote in November 2028. Voter approval in that election would then start a new period with fiscal year 2030. The law itself expires January 1, 2032.
Would the caps lower my property tax bill?
Not necessarily. A cap can still allow local school taxes to rise. Your own tax bill also depends on the value of your home, the tax base, and other local and state tax charges. Question 2 does not cap your entire property tax bill.
Could the caps affect schools?
Yes. The statute excludes classroom instruction and school services from the definition of SAU central office spending. But the separate school tax levy cap could still limit money available for the whole school budget. School boards might face difficult choices (such as cutting staff, extracurriculars, athletics, etc.) if non-discretionary costs (such as health insurance premiums, legally mandated special education services, gas and diesel prices, etc.) rise faster than the allowed levy. The ballot wording does not promise that classroom services will stay unchanged.
Supporters believe caps can slow tax growth and push school leaders to control costs. Opponents worry that rising costs for transportation, health coverage, or student services could force cuts or make budget planning harder. Both sides want financially strong communities and good public education but disagree on the best way to reach those goals.
Can a district spend above its cap?
Yes, if it follows the legal override process. Districts with annual meetings generally need at least 60% yes votes on the applicable appropriation question at their annual meeting. Certain charter communities follow their charter supermajority rules. The New Hampshire Department of Revenue Administration checks compliance and can withhold tax rate approval if a district exceeds a cap without a valid override.
How may this affect the value of my home?
Supporters point out that high property taxes may deter potential buyers.
Opponents point out that the perceived value of the school system, which is likely to suffer if budgets are insufficient to provide a quality education, is a factor in the value of a home.
Why is this question on the ballot?
This proposal is a result of HB 1300, which passed in the most recent legislative session and was signed into law by Gov. Ayotte in July. is intended to address New Hampshire’s high property taxes.
Why are property taxes so high?
New Hampshire relies heavily on property taxes to fund public schools.
In the 2023–24 school year, approximately 70% of school district revenue came from property taxes raised locally, including the Statewide Education Property Tax. State funding covers only part of school costs and that portion has been shrinking over time, leaving communities to bridge much of the gap. Property tax is the only option communities have to raise funding.
Don't communities already have the ability to enact tax caps?
Yes. Existing law allows locally initiated tax-cap votes through the annual-meeting process, with public hearings and a three-fifths approval threshold, and some NH towns already have a cap through this process. The November question creates a different route: state law requires it to appear without a local petition.
Questions to ask before voting
· How much of our current school budget comes from local property taxes?
· How much does our SAU spend on the central office under the law’s definition?
· How would inflation, construction, and changing state aid affect our district?
· What changes would our school board consider if a cap limits available revenue?
Table 1
How does this work when an SAU serves more than one town and/or school district?
Simple Decision Guide
This video from the NH School Administrators Association explains the NH Tax Cap Law, HB1300.
Sources and Accuracy Notes
Primary law: New Hampshire RSA 32:5-i (2026), https://gc.nh.gov/rsa/html/III/32/32-5-i.htm. Official HB 1300 guidance: https://www.sos.nh.gov/hb-1300-ballot-question. Question 1: CACR 13 and the 2026 voter guide at https://newhampshirebulletin.com/voter-guides/ballot-measures/2026-question-1/. Question 2 official wording and context: https://newhampshirebulletin.com/voter-guides/ballot-measures/2026-question-2/. School funding statistics and history: https://nhfpi.org/resource/education-in-new-hampshire-fiscal-policies-in-2025/and https://nhfpi.org/blog/new-hampshire-policy-points-2025-state-budget/
This guide paraphrases the ballot questions. Check your actual town ballot for the exact legal text. The calculations use the enacted RSA 32:5-i, not earlier drafts of HB 1300.